Get the rental financed without wondering where it stands.
We broker short-term rental loans through lenders who underwrite on the property's income, not your day job. Real terms back in about two business days, no credit pull to start.
Lenders who fund rentals dailyDSCR and second-home loans underwritten on the property's income, not just your W2.
Terms in days, not weeksSend one property and get real numbers back, usually inside two business days.
No obligation, no credit pullNothing touches your credit until you apply.
The whole process, step by step.
13 steps from your first quote to the recorded loan, across two boards: Quotes, then Deals. The app runs exactly these, and every step says whose move it is.
Whose moveYouonly you can do theseGoDoorthe numbers, the lender and the chasing
Quotes
Your quote
Your numbers in, our read of them out. No credit pull.
Finish quoteYouThe property, the loan, the rent and you. About five minutes.
Under reviewGoDoorWe read it the way an underwriter will, before we price it.
Term sheet
What a lender is prepared to do, in writing, and the rate you choose.
ProcessingGoDoorWe price it with lenders and write your term sheet.
Review, choose ratesYouCompare the options and choose the rate you want.
Deals
Application
The documents, our review of them, then your file with the lender.
Document gatheringYouYour REO schedule, driver's license and credit authorization.
Document reviewGoDoorWe check every document before the lender sees it.
RegisteringGoDoorWe register your file with the lender and order the appraisal.
Underwriting
The lender verifies everything, approves with conditions, then checks it all once more.
SubmittedGoDoorThe underwriter verifies credit, value, rent, title and insurance.
Conditional approvalYouApproved, with a list of conditions to clear.
Final reviewGoDoorThe lender's last check, then clear to close.
Closing
Signed, funded, paid out and recorded.
Being packagedGoDoorLoan documents, title and insurance, in one package. You sign; the lender wires the loan.
Final dispersalGoDoorEscrow pays everyone out.
RecordedRecorded with the county. Done.
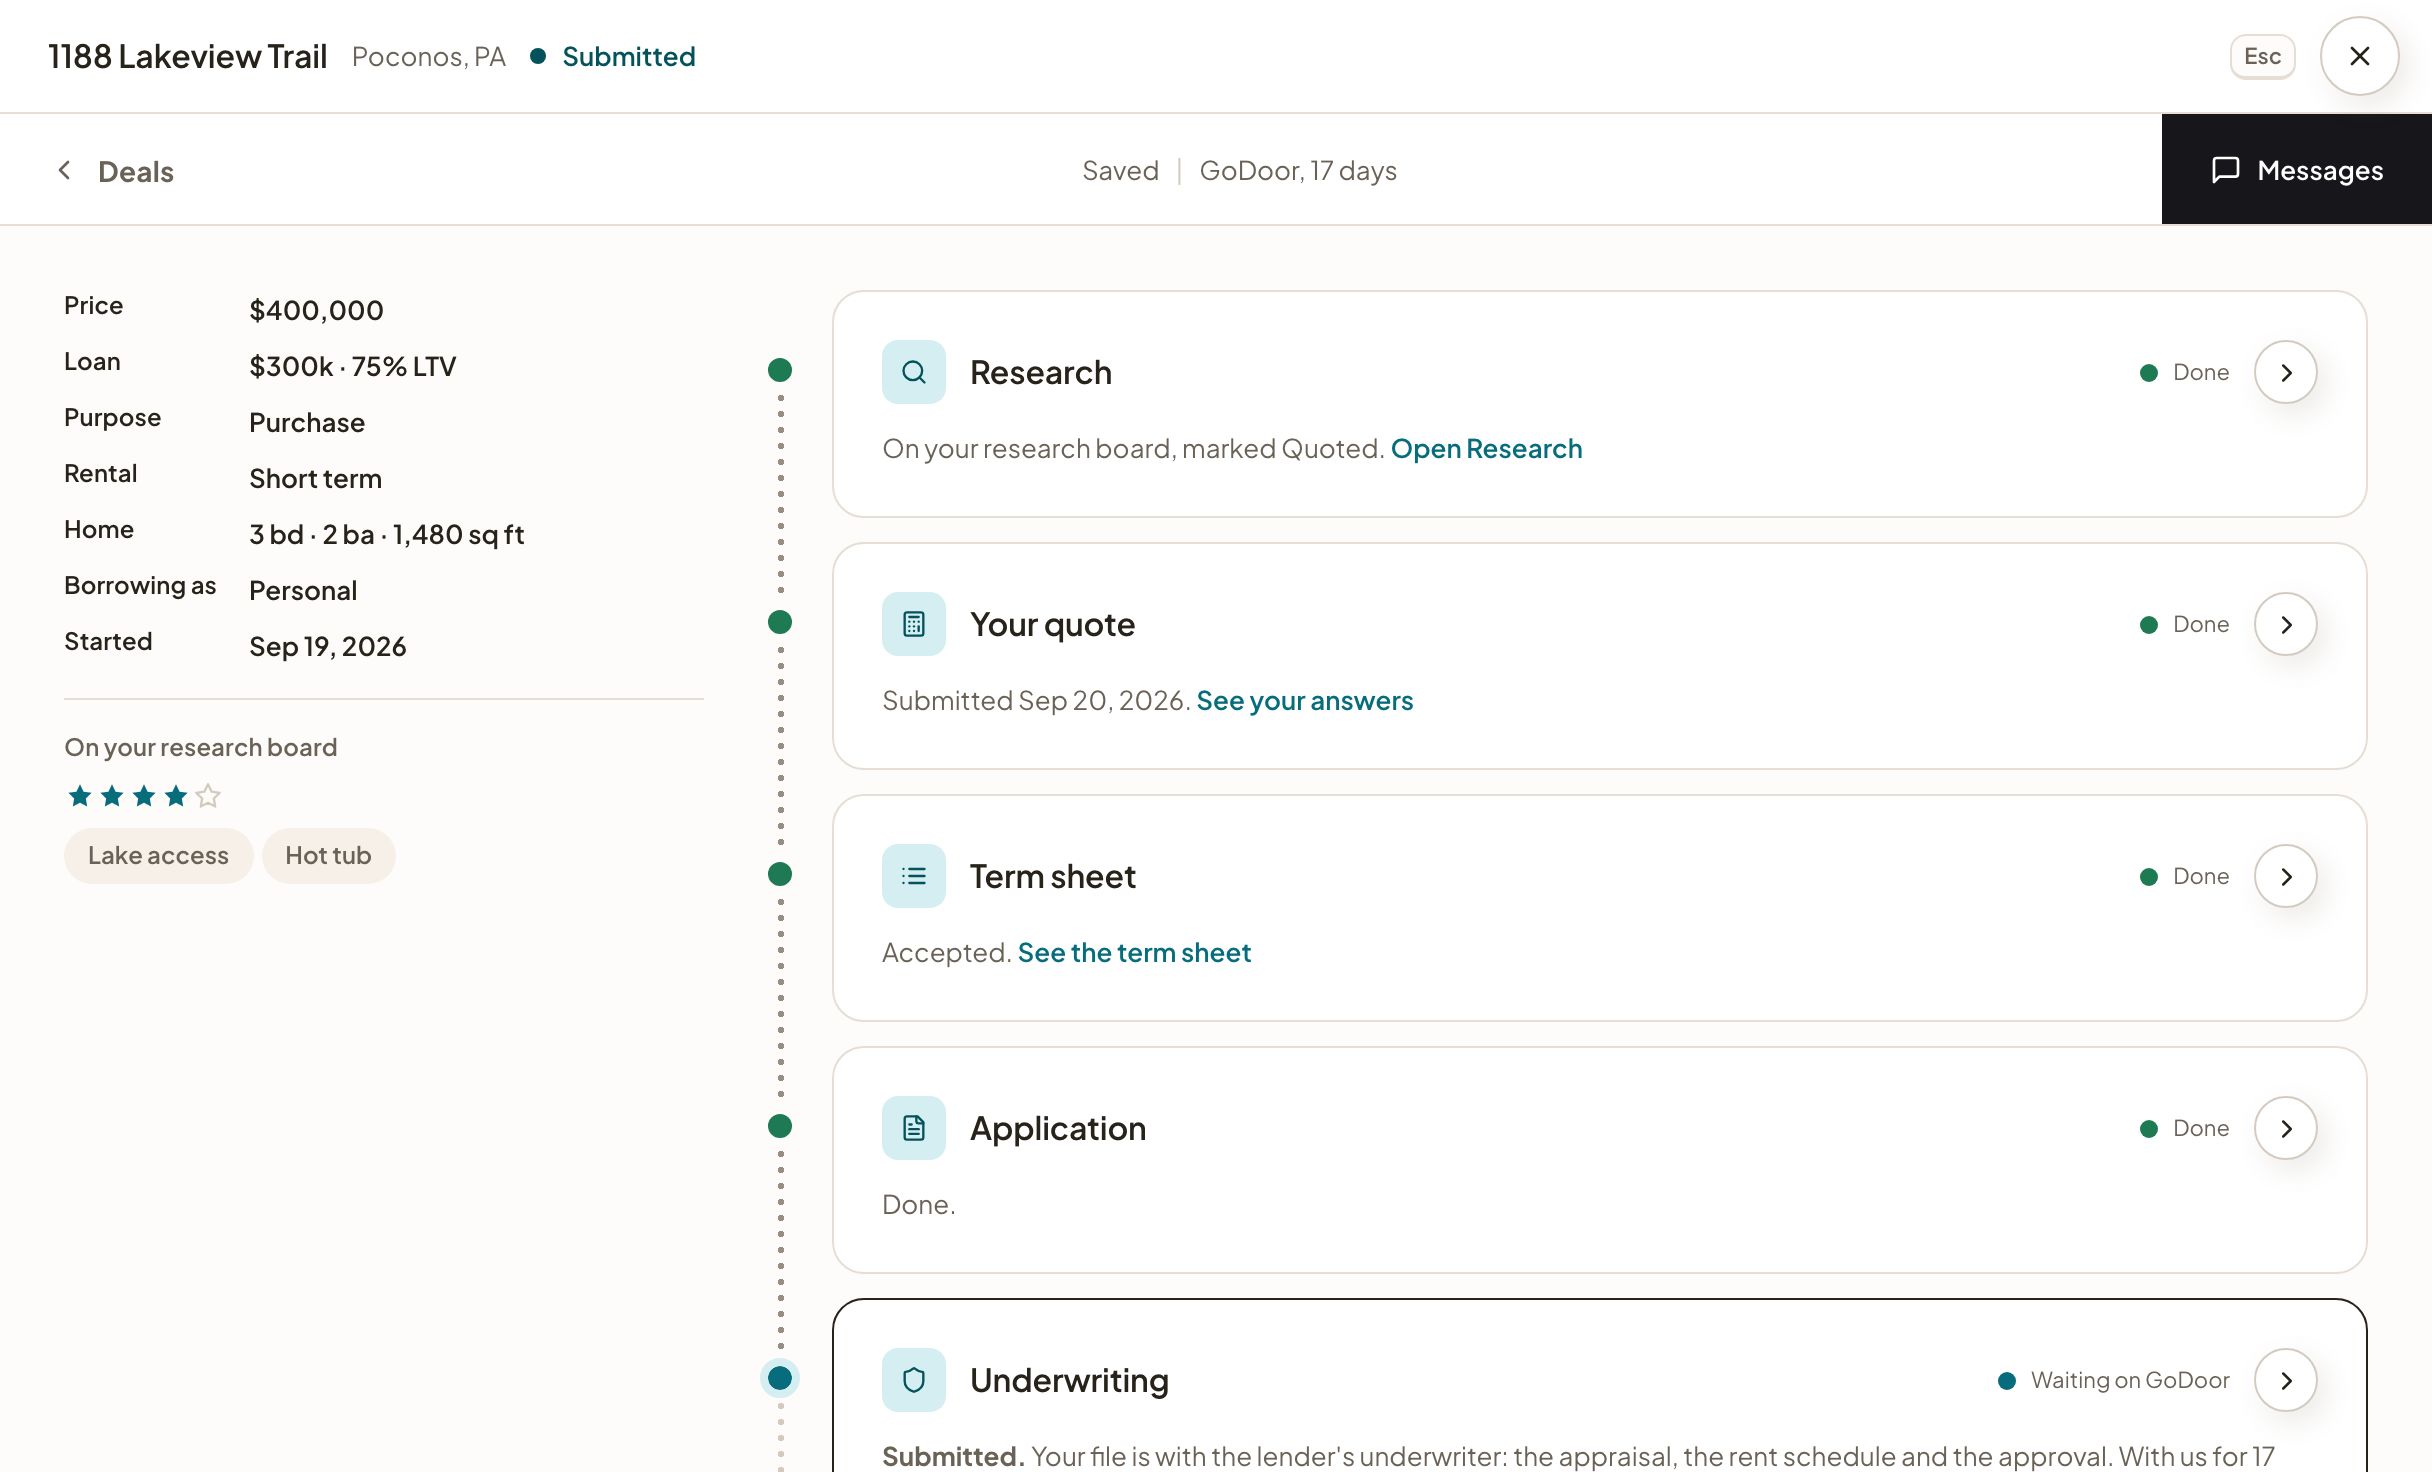
The same steps inside the app. Each property is one file: where it stands, and whose move it is.
What to expect.
What we need up front
An address, your credit band, and a rough figure for reserves. Ten minutes, once.
How long each stage takes
Terms in two business days. Appraisal takes a week to ten days. Contract to funded is about a month.
The surprise that shows up most
The appraiser's rent schedule comes in under projection. Fix it with more down or a lower price.
What actually slows a deal
Documents, not underwriting. We chase the outstanding list so nothing sits.
Questions that come up on every first call.
How do lenders calculate DSCR on a short-term rental?
Gross rents divided by PITIA: principal, interest, taxes, insurance and any HOA dues. On a refinance the rent side is usually the trailing 12 months of booking statements; on a purchase it is the appraiser's short-term rental analysis, which many lenders haircut for vacancy and management. Most programs want 1.00 to 1.25. Some will go below 1.00 in exchange for lower leverage and a higher rate.
How much leverage can I get, and what moves the rate?
Purchases typically top out at 75 to 80% LTV, cash-out refinances at 70 to 75%. Pricing moves on your FICO band, LTV, DSCR, loan size and the prepayment penalty you accept: a five-year step-down buys a lower rate than a three-year or none. Short-term rental programs often price a little above the long-term rental equivalent.
DSCR, second home, or conventional investment: which fits?
Second-home loans price best but assume you occupy the property, and you cannot qualify on its rental income, so a year-round STR is a poor fit. Conventional investment loans qualify on your debt-to-income and cap out at ten financed properties. DSCR qualifies on the property alone, closes in an LLC and has no property-count cap, which is why most operators past their second or third door end up there.
What reserves and track record will a lender want?
Plan on 6 to 12 months of PITIA in reserves per financed property, more on larger loans or a first investment property. Many STR programs also ask for hosting history or a professional manager; without either, some cut leverage by five to ten points rather than decline.
Can I close in an LLC, and will I sign a personal guarantee?
Yes to both, usually. DSCR loans routinely close in an entity, and each member with 20% or more ownership typically guarantees the loan and has credit pulled. Your entity documents (articles, operating agreement, EIN, good standing) are collected once in your profile and reused on later files.
How do permit caps and local rules affect the loan?
Underwriting assumes the income is legal. Where a market caps permits or bars non-owner-occupied rentals, the lender will ask whether the permit transfers with the sale, and may underwrite to long-term rent if it does not. Confirm transferability before you are under contract; it is the most common reason an STR file falls back to long-term numbers.
Does GoDoor's revenue projection count as income?
No lender underwrites to a third-party projection, ours included. On a purchase the appraiser's rent schedule sets the number; on a refinance, your booking statements do. Our projection is for screening deals and for knowing roughly what the appraisal needs to show.
What does GoDoor charge?
The research tools are free, and nothing is charged before you choose a lender. When you do, every fee is on the term sheet: origination and any discount points you buy down with, processing, and a flat $1,995 underwriting fee, whatever the lender charges behind it.
Nothing until it closes.
Partners pay us when a deal funds. You pay nothing, so we place you with the lender who fits, not the one paying the most this quarter.